~ By Ishika Dutta
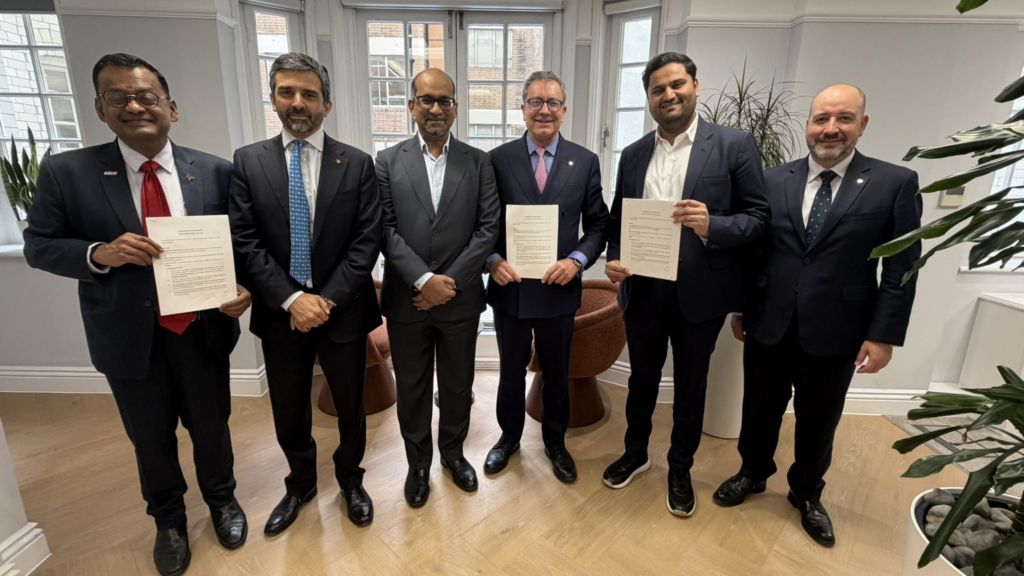
Kutch Copper Ltd (KCL), a unit of Adani Enterprises, has signed an MoU with Chile’s Corporación Nacional del Cobre (Codelco) to explore the Kaburkaala project in the Calama copper belt of Chile’s Antofagasta Region. The signing took place at LME Week 2026 in London, in the presence of Jeet Adani, Director of Kutch Copper, Dr Vinay Prakash, CEO of Adani Natural Resources, and Bernardo Fontaine, Chairman of Codelco.
On paper this is an exploration MoU. In practice it is a move to connect upstream copper in Chile with the smelter complex at Mundra, and it lands at a time when India’s copper story is being rewritten.
Why Chile and why Codelco
Chile is the world’s largest copper producer and Codelco is the largest copper mining company in Chile. For India, Chile is also already the biggest source of copper concentrate, at roughly 0.6 million tonnes of the 1.44 million tonnes India imported in 2025. If the exploration fructifies, Mundra gets a continuous, long-term feed of concentrate from a partner that sits at the top of the supply chain.
This is not the first step between the two sides. Earlier, Codelco and Adani agreed concentrate supply for the Mundra smelter, and in November 2025 Kutch Copper and Codelco signed an MoU to evaluate three projects in the Antofagasta and Atacama regions. Kutch Copper has also signed a non-binding MoU with Caravel Minerals for a copper project in Western Australia. The pattern is clear: lock in concentrate from more than one geography before the smelter reaches full scale.
One caution. An MoU to explore is not a mine, and Kaburkaala still has to prove itself. Time will tell how much of it turns into tonnes.
The smelter this feeds
The Kutch Copper complex at Mundra, Gujarat, is a roughly $1.2 billion project with a 500,000 tonnes per annum refined copper capacity, among the largest single-location copper smelters in the world. Its Grade A cathodes were registered with the London Metal Exchange in July 2026, so Adani Copper can now be delivered against LME contracts. The stated ambition is to scale towards 1 million tonnes a year, with about 115 MW of renewable energy planned to be integrated at the site.
India’s installed refined copper capacity is now around 1.15 million tonnes a year, led by Hindalco, Vedanta and Kutch Copper. A single new smelter at Mundra is therefore a large share of the national total.
India’s copper numbers
India’s copper demand reached about 1.88 million tonnes in FY2025, up 9.3%, and rose a further 12% to about 2.1 million tonnes in FY2026. The International Copper Association expects demand to keep growing at about 10% a year. Domestic refined production in FY2026 was about 704,000 tonnes, up 23%, and met roughly 58% of demand. Scrap supplied the other 42%, and about 274,000 tonnes of that scrap was imported.
The weak link is the ore. Concentrate made up about 85% of India’s copper imports in 2025, and industry executives accept that India will not be self-sufficient in concentrate because it lacks the domestic resources. Concentrate imports rose about 23% in 2025 to 1.44 million tonnes. India’s refined imports have run at 300,000 to 500,000 tonnes a year for the past decade, and are expected to shrink as new smelting capacity ramps up. A recent industry panel estimated that India could account for around 30% of future global growth in refined copper consumption.
So the strategy is straightforward. India will import concentrate and win on smelting and refining, and the Chile link is what makes that workable.
Why copper matters for development and industry
Copper is the metal of electrification. It carries power in generation, transmission, transformers, motors, cables, buildings and every electronic device. Electrical equipment is the single largest consumer in India, followed by construction, automobiles and consumer durables.
The energy transition makes it more important, not less. A conventional passenger car uses roughly 8 to 16 kg of copper, while a battery electric car uses about 70 kg or more, nearly five times as much. Solar and onshore wind need on the order of 3 tonnes of copper per MW, and offshore wind needs more than 8 tonnes per MW. Data centres, grids and charging networks add to this. For a country planning hundreds of gigawatts of renewable capacity and a large EV push, copper is a question of strategic supply, much like fuel, not just industrial raw material.
Before and after Sterlite
To understand why this MoU matters, go back to Tuticorin.
Before 2018. Vedanta’s Sterlite smelter at Thoothukudi had a capacity of 400,000 tonnes a year, roughly 40% of India’s copper smelting capacity. India was a net exporter of refined copper for about 18 years and sat among the top five exporters of copper cathodes. In FY2018 India’s net exports of refined copper were about 334,000 tonnes, and it exported around half of what it produced.
The protests. Local residents had long alleged pollution from the plant, and the protests grew against its proposed expansion to double capacity. On 22 May 2018, police opened fire on a large crowd and at least 13 people were killed. The Tamil Nadu government and the TNPCB ordered the plant closed days later, on 28 May. It is important to state this plainly: this was a real grievance and a real tragedy, and the courts took the environmental record seriously. In February 2024 the Supreme Court dismissed Vedanta’s appeal, calling the plant a chronic violator of pollution laws, and in October 2024 it dismissed the review petition. The closure stands.
After 2018. The national numbers moved quickly. Refined copper production fell 46% in FY2019, exports fell about 87% and imports rose about 131%. India became a net importer of refined copper for the first time in 18 years, with a net import of about 44,000 tonnes in FY2019 and about 115,000 tonnes in FY2020. Estimates put the extra foreign exchange outflow at over a billion dollars a year, and analysts noted that export markets such as China shifted to other suppliers. Locally, roughly 4,000 direct employees and an estimated 20,000 people in transport, ancillary and trade lost income.
The lesson. I read the Sterlite episode as a reminder that scale and compliance have to travel together. India lost 40% of its smelting capacity overnight because one operator’s environmental record could not survive public scrutiny. The rebuild since then has been driven by Hindalco, Vedanta’s other operations and now Adani at Mundra, a coastal site with a modern plant, an LME-grade product and a plan to run partly on renewable power. The credibility of that model rests on environmental performance staying clean over the long run. If Kutch Copper delivers on that, it shows India can build heavy industry without repeating Tuticorin. If it does not, the same political risk returns.
The broader point is that a net exporter became a net importer through the closure of a single plant. That tells you how thin the national copper system was, and why diversified concentrate supply, from Chile and from Australia, and more than one smelting hub now matter so much.
What to watch
Three things will decide whether this MoU matters. First, whether Kaburkaala moves from exploration to a defined resource and offtake. Second, how fast Mundra ramps up and moves towards its larger capacity. Third, whether India’s refined imports actually decline as the industry expects. If all three go right, India will move from being a copper importer back towards being a net exporter of refined metal, with its upstream supply secured in Chile.